Trust parties, corpus and pass-through taxation

Trust parties, corpus and pass-through taxation

Published September 28, 2026

Trust parties, corpus and pass-through taxation

On this page

Trust roles and tax reporting

A trust separates the person who supplies property, the person who controls and administers it, and the people who benefit from it. Tax rules must identify whether trust items are reported by the grantor, the trust, or a beneficiary.

TCP questions in Entity Tax Compliance use these distinctions before applying the trust’s tax status and distribution rules. Ava is the grantor, Ben is the trustee, and Cara is the beneficiary. Ava transfers $100,000 of cash as the initial corpus.

Types of trusts and their tax status determines whether the trust is simple, complex, or grantor. This chapter identifies the parties and follows the tax path.

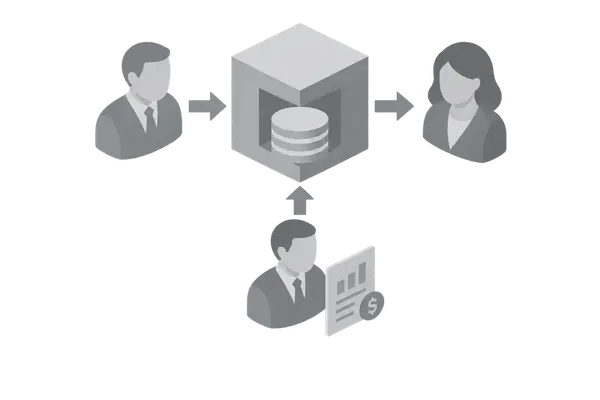
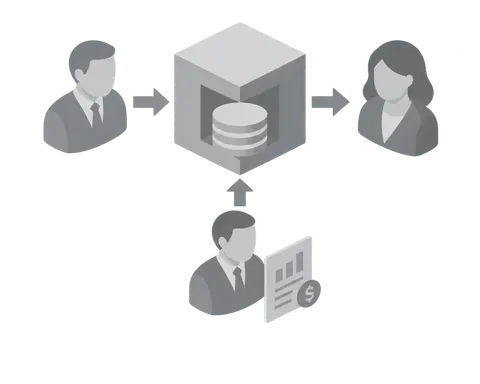
Separating legal control from economic benefit makes the trust structure clear before tax rules are applied. The diagram places the people, property, and tax path together so each part can be defined precisely.

Trust property, control and tax rules

The diagram shows how the grantor, corpus, trustee, and beneficiaries relate. It also shows how trust items follow the applicable tax rules.

Loading diagram…

🔑 RULE: Generally, an arrangement will be treated as a trust under the Internal Revenue Code if its purpose is to vest in trustees responsibility for the protection and conservation of property for the beneficiaries.

The structure connects trust property to the people who control it and benefit from it. Types of trusts and their tax status supplies the classification that determines which tax path applies. The clue words for each part follow.

Trust roles, corpus and tax treatment

The table turns each diagram node into a definition that can be recognized in a fact pattern. It uses the trust terms for each role, corpus, and tax treatment.

Uniform Trust Code definitions describe a beneficiary as a person with a present or future beneficial interest. A settlor or grantor creates or contributes property to a trust. A trustee serves in the fiduciary role.

Corpus means the trust property or principal held for beneficiaries. It includes the initial $100,000 and later additions. Corpus is not the income produced by that property.

IRC §641(b) provides that trust taxable income is computed like an individual’s taxable income, except as otherwise provided. For a grantor trust, IRC §671 includes items attributable to the owned portion in the taxable income and credits of the grantor or other owner.

For a non-grantor trust, IRC §§661-662 generally allow a distribution deduction for qualifying distributions. Corresponding amounts are included in the beneficiary’s income, subject to distributable net income rules. IRC §662(b) keeps the character of amounts the same in the beneficiary’s hands.

Retained items may remain taxable to the trust under IRC §641. Receipts are not allocated between income and corpus here. That work belongs to Trust accounting income and corpus allocation. The amount carried out and the related deduction belong to Distributable net income and the distribution deduction.

PartWhat it coversClue words in a scenario
GrantorThe person who creates the trust or contributes property to it.creates, establishes, transfers, contributes, funds
TrusteeThe fiduciary who holds legal title, manages the trust property, keeps records, and acts under the trust terms.legal title, fiduciary, manages, invests, administers, accounts
BeneficiariesThe people with present or future beneficial interests, whether vested or contingent, who may receive income or principal.receives, current income, remainder, beneficial interest, contingent
CorpusThe property or principal held in trust for beneficiaries, including the initial funding and later additions; it is distinct from income produced by the property.property held, principal, assets, initial funding, additions, remainder
Pass-through taxationTax items follow the applicable trust rules: grantor-trust items are reported by the grantor, qualifying distributed DNI is generally included by beneficiaries, and retained items may remain taxable to the trust.distributed, DNI, Schedule K-1, distribution deduction, grantor reports, retained income

Corpus identifies the property being managed. Pass-through taxation explains what happens to trust items, while later chapters determine allocation and exact DNI amounts.

Identifying trust roles and corpus

Each scenario highlights one part of the structure. The other choices are different parts of the same structure.

Practice

Ava signs the trust instrument and transfers the $100,000 initial property to the arrangement. Which part of the trust structure is Ava?

Ben holds legal title to the trust property, invests the property, keeps records, and makes distributions under the trust terms. Which part of the trust structure is Ben?

Cara has a present right to receive trust distributions and a future right to the property remaining when the trust ends. Which part of the trust structure is Cara?

A non-grantor trust earns $8,000 of interest and distributes $5,000 to Cara. Which part of the trust structure describes the rule that may cause the distributed amount to be included by Cara while retained items may remain taxable to the trust?

The scenarios distinguish the people, the property, and the tax treatment before allocation or DNI calculations are applied.

Trust roles, corpus and pass-through taxation

  • Grantor: creates or funds the trust.
  • Trustee: holds legal title and administers the trust property.
  • Beneficiaries: hold present or future beneficial interests.
  • Corpus: the property or principal held in trust, distinct from the income it produces.
  • Pass-through taxation: applicable rules may place trust items with the grantor, the trust, or beneficiaries receiving qualifying distributions.

These five lines preserve the structure needed for Trust accounting income and corpus allocation, which separates receipts and disbursements. Distributable net income and the distribution deduction determines the amount carried out and deducted.

Unlock the full lesson and continue reading

Signup to continue reading this lesson and unlimited access questions, flashcards, AI notes, and more

Scan to download app

Scan to download
UNLOCK FREE ACCESS

Practice Questions: Trust parties, corpus and pass-through taxation

  1. 1. A complex trust terminates in 2025 and distributes its remaining corpus 75% to Beneficiary J and 25% to Beneficiary K. At termination, the trust has a $40,000 unused net operating loss carryover, a $12,000 capital loss carryover, and $8,000 of excess deductions on termination. What amounts pass through to Beneficiary J?

    • A. $30,000 net operating loss, $9,000 capital loss, and $6,000 excess deductions
    • B. $40,000 net operating loss, $12,000 capital loss, and $8,000 excess deductions
    • C. $30,000 net operating loss, $9,000 capital loss, and no excess deductions
    • D. $36,000 net operating loss, $9,000 capital loss, and $6,000 excess deductions
    Show answer

    Answer: A. $30,000 net operating loss, $9,000 capital loss, and $6,000 excess deductions

    $30,000 net operating loss, $9,000 capital loss, and $6,000 excess deductions - Under IRC § 642(h), unused net operating loss and capital loss carryovers and excess deductions pass to the beneficiaries when the trust terminates. - Beneficiary J’s 75% share is $40,000 × 75% = $30,000, $12,000 × 75% = $9,000, and $8,000 × 75% = $6,000. $40,000 net operating loss, $12,000 capital loss, and $8,000 excess deductions - These amounts assign 100% of each trust attribute to J rather than J’s stated 75% share. - The single slip is failing to allocate any portion to Beneficiary K, who receives the remaining 25% of the corpus. $30,000 net operating loss, $9,000 capital loss, and no excess deductions - The loss amounts correctly use J’s 75% share of the $40,000 and $12,000 carryovers. - The single slip is omitting excess deductions on termination: $8,000 × 75% = $6,000 also passes to J. $36,000 net operating loss, $9,000 capital loss, and $6,000 excess deductions - The capital loss and excess deductions use the stated 75% share correctly. - The $36,000 net operating loss results from applying 90% to $40,000 instead of J’s 75% share, which yields $30,000.

  2. 2. During 2025, an exempt public charity received $100,000 of rent from an unrelated tenant using a parcel of land in an activity unrelated to the charity's exempt purpose. Direct rental expenses were $40,000. The land's average acquisition indebtedness was $250,000, and its average adjusted basis was $500,000. The lease involved no personal property or tenant services. What amount is included in unrelated business taxable income before the specific deduction?

    • A. $30,000
    • B. $20,000
    • C. $50,000
    • D. $0
    Show answer

    Answer: A. $30,000

    $30,000 - The debt-financed percentage is 50%: $250,000 average acquisition indebtedness divided by $500,000 average adjusted basis. - Applying that percentage to $100,000 of rent and $40,000 of direct expenses gives $30,000 before the specific deduction: $50,000 − $20,000. $20,000 - $20,000 is 50% of the $40,000 direct rental expenses. - It is the allocable deduction, not the amount included in unrelated business taxable income. $50,000 - $50,000 is the debt-financed share of the $100,000 gross rent. - This answer fails to subtract the $20,000 share of direct rental expenses. $0 - Rent from land without personal property or tenant services generally qualifies for the rental-income exclusion. - The debt-financed property rules nevertheless bring the applicable share of this rent, less allocable expenses, into unrelated business taxable income.

  3. 3. In 2025, Reed transfers equipment with an adjusted tax basis of $70,000 and a fair market value of $150,000 to a newly formed C corporation solely for all its stock. The corporation assumes a $90,000 equipment loan incurred for a bona fide business purpose. What are Reed's recognized gain and adjusted basis in the stock immediately after the transfer?

    • A. Recognized gain of $0 and stock basis of $0
    • B. Recognized gain of $20,000 and stock basis of $0
    • C. Recognized gain of $20,000 and stock basis of $20,000
    • D. Recognized gain of $80,000 and stock basis of $60,000
    Show answer

    Answer: B. Recognized gain of $20,000 and stock basis of $0

    Recognized gain of $20,000 and stock basis of $0 - Because the transfer otherwise qualifies for nonrecognition, Reed recognizes gain only to the extent the $90,000 liability exceeds the equipment’s $70,000 basis: $20,000. - Reed’s stock basis is $70,000 transferred basis + $20,000 recognized gain − $90,000 liability assumed = $0. Recognized gain of $0 and stock basis of $0 - The $0 gain disregards the rule requiring recognition when an assumed liability exceeds the transferred property’s basis by $20,000. - The $0 stock basis is correct, but only after adding the $20,000 recognized gain and subtracting the full $90,000 liability. Recognized gain of $20,000 and stock basis of $20,000 - The $20,000 gain correctly equals the $90,000 liability minus the equipment’s $70,000 basis. - The $20,000 stock basis results from subtracting only $70,000, rather than the full $90,000 liability, from $70,000 + $20,000. Recognized gain of $80,000 and stock basis of $60,000 - The $80,000 is the realized gain ($150,000 fair market value − $70,000 basis), not the gain recognized under the liability rule. - The $60,000 is the stock’s value after the loan ($150,000 − $90,000), not its adjusted tax basis.

  4. 4. During 2025, a domestic C corporation purchased inventory from an unrelated U.S. manufacturer for $120,000 and sold it to a foreign customer for $200,000. The corporation performed no production activities. Under the sales contract, title and risk of loss passed to the customer at its foreign warehouse. What amount and source of gross income result from the sale?

    • A. $0 of foreign-source gross income
    • B. $80,000 of U.S.-source gross income
    • C. $80,000 of foreign-source gross income
    • D. $200,000 of foreign-source gross income
    Show answer

    Answer: C. $80,000 of foreign-source gross income

    $80,000 of foreign-source gross income - Gross income from the sale is $80,000: the $200,000 sales price less the $120,000 inventory cost. - Because the corporation purchased the inventory for resale and title passed at the foreign warehouse, the income is foreign-source. $0 of foreign-source gross income - Treating the U.S. manufacturer’s location as the source would incorrectly produce $0 of foreign-source income. - The corporation earned $80,000 of gross income, and the contract places the sale abroad when title passed at the foreign warehouse. $80,000 of U.S.-source gross income - Subtracting $120,000 from $200,000 correctly gives $80,000 of gross income. - Sourcing that income to the United States because the inventory came from a U.S. manufacturer overlooks where title passed. $200,000 of foreign-source gross income - The $200,000 sales price is gross receipts, not gross income from the inventory sale. - Subtracting the $120,000 inventory cost leaves $80,000 of foreign-source gross income.

  5. 5. A calendar-year C corporation has a $45,000 net capital loss for 2025. The corporation reported net capital gains of $10,000 in 2022, $20,000 in 2023, and $5,000 in 2024. It has no other capital gains or losses. How much of the 2025 net capital loss may the corporation carry forward to 2026?

    • A. $0
    • B. $10,000
    • C. $35,000
    • D. $45,000
    Show answer

    Answer: B. $10,000

    $10,000 - A C corporation carries a net capital loss back three years to offset capital gains before carrying any remainder forward. - The 2025 loss offsets $10,000 in 2022, $20,000 in 2023, and $5,000 in 2024, leaving $45,000 − $35,000 = $10,000 for 2026. $0 - The three carryback years have only $35,000 of capital gains, so they cannot absorb the full $45,000 loss. - A zero carryforward incorrectly ignores the corporation’s ability to carry the unused $10,000 forward. $35,000 - Subtracting only the 2022 gain produces $45,000 − $10,000 = $35,000. - That calculation omits the $20,000 gain in 2023 and the $5,000 gain in 2024, which also absorb the loss. $45,000 - Carrying forward the entire $45,000 ignores the required carrybacks to 2022, 2023, and 2024. - Those years’ capital gains absorb $35,000, leaving only $10,000 to carry forward.

  6. 6. During 2025, a domestic C corporation earned a $200,000 consulting fee under one service contract. Employee time records establish that 70% of the services were performed in the United States and 30% were performed in Germany. What amount of the fee is foreign-source gross income for U.S. federal income tax purposes?

    • A. $0
    • B. $60,000
    • C. $140,000
    • D. $200,000
    Show answer

    Answer: B. $60,000

    $60,000 - Consulting fees are sourced where the services are performed, so the portion performed in Germany is foreign-source income. - The time records allocate 30% of the $200,000 fee to Germany: $200,000 × 30% = $60,000. $0 - A domestic corporation can earn foreign-source service income; its U.S. residence does not make the entire fee U.S.-source. - Treating all $200,000 as U.S.-source disregards the 30% of services performed in Germany. $140,000 - $200,000 × 70% = $140,000, but that percentage represents services performed in the United States. - This answer reverses the time-record allocation and counts the U.S.-source portion as foreign-source income. $200,000 - Treating the entire contract fee as foreign-source ignores that 70% of the services were performed in the United States. - Only the 30% performed in Germany is foreign-source, even though both portions were earned under one contract.

Flashcards: Trust parties, corpus and pass-through taxation

  1. 1. Are expenses and fees allocable to tax-exempt income deductible by a trust?

    Show answer

    No. Expenses and fees allocable to tax-exempt income are not deductible for either a simple or a complex trust.

  2. 2. How are unused net operating losses of a trust treated?

    Show answer

    An NOL incurred by a trust generally remains with the trust and does not pass through to beneficiaries merely because it is unused. When the trust terminates, an NOL carryover not deductible by the trust is allowed to beneficiaries succeeding to the trust property under the termination-year rules.

Everything you need for CPA prep

Get full Oncourse access with lessons, practice questions, flashcards and AI study tools.

GET STARTED FOR FREE
75% OFFLimited time offer
GET 75% OFF