Yield Curve Strategies CFA Flashcards - Medical Study Cards
Master Yield Curve Strategies with Oncourse flashcards. These spaced repetition flashcards are designed for medical students preparing for NEET PG, USMLE Step 1, USMLE Step 2, MBBS exams, and other medical licensing examinations.
Yield Curve Strategies Flashcard Deck - 10 Cards
Flashcard 1: Adjusting Dollar Duration
Answer: Dollar Duration calculates the change in value of a portfolio for a 1% change in interest rates.
DD = (duration)(0.01)(price)
Dollar duration must occasionally adjust the portfolio's dollar duration. There are two primary steps:
1. Calculate the new dollar duration of the portfolio
2. Calculate the rebalancing ration. Subtracting 1 from this ratio gives the percent change to make in the holding in each asset in the portfolio.
Rebalancing Ratio = (Target DD/New DD)
Flashcard 2: Duration Contribution
Answer: Managers often rely on value weight to determine exposure. An alternative way to measure exposure is to measure the contribution to duration of the portfolio.
Duration Contribution is the product of the duration of an asset and the weight in the portfolio.
Flashcard 3: Key Rate Duration\
*Bond Primary Risk Factors*
Answer: Key Rate Duration breaks the yield curve into a finite number of maturity points and analyzes change in price of a security if only one of those points on the yield curve changes.
Flashcard 4: Duration\
*Bond Primary Risk Factors*
Answer: Duration measures exposure to interest rate risk as measured by small parallel changes in the yield curve. For larger changes in rates, matching convexity will improve results but convexity also assumes parallel shifts.
Think of interest rate risk as movement in the general level of interest rates and yield-curve risk as non-parallel changes in rates and the yield curve.
Flashcard 5: The Shape of the Yield Curve and the Business Cycle (4)
Answer: steep at the bottom of the cycle\
flatten during the expansion\
very flat or even inverted at the peak\
re-steepen during the subsequent contraction
Flashcard 6: Effective duration\
Effective spread duration of a portfolio\
Key rate duration\
Rate duration of an FRN\
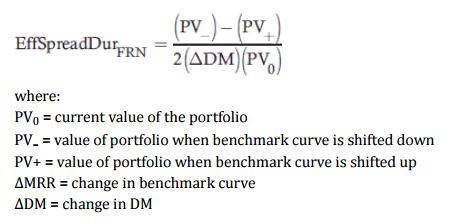
Spread duration of an FRN
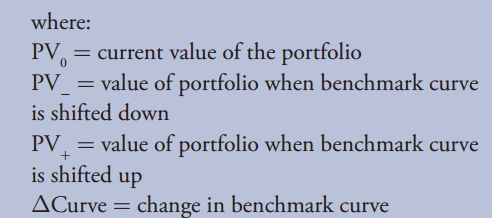
Answer: Effective duration (parallel shift - embeded option)\
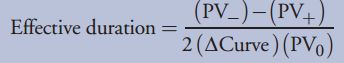\
\
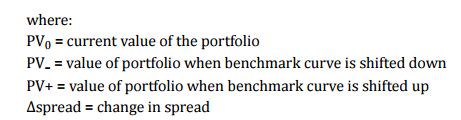
Effective spread duration of a portfolio\
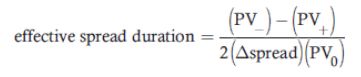\
\
Key rate duration (non-parallel shift)\
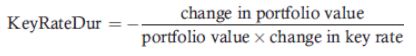\
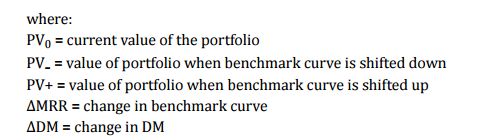
Rate duration of an FRN\
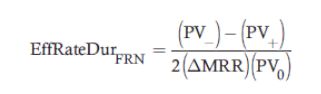\
\
Spread duration of an FRN (corporate FRN will fall in price if the credit quality of the issuer declines)\
discount margin (DM) - required return of investors above the current MRR\
Flashcard 7: Butterfly spread (curvature of the yield curve)\
Increase means?
Answer: butterfly spread = −(short-term yield) + (2 × medium-term yield) − long-term yield
an increase in the butterfly spread means a negative butterfly twist
Flashcard 8: %Δ value for parallel shifts in the yield curve
Answer: %Δ value = –MD Δy
Flashcard 9: Hedge Funds - Fixed-income arbitrage\
type?
Answer: Relative value
Takes advantage of temporary mispricing of fixed-income instruments by going long undervalued securities and short overvalued securities.
- Yield curve trades - go long and short fixed-income investments in order to profit from the anticipated yield curve steepening or flattening.
- Carry trade - the portfolio manager shorts a low-yielding security and goes long a high-yielding security.
Flashcard 10: Laddered portfolios (4)
Answer: - Purchase bonds that mature in 1, 2, 3, 4, and 5 years. As each bond matures, the proceeds are typically reinvested into a new long-term bond, maintaining the ladder.
- Balance between the barbell and bullet strategies.
- Provide regular access to cash.
- Reduced Interest Rate Risk: When rates rise, maturing bonds can be reinvested at higher yields, and when rates fall, the investor benefits from the higher yields on longer-term bonds still held in the portfolio.
Keywords: Yield Curve Strategies flashcards, medical flashcards, NEET PG preparation, USMLE Step 1 flashcards, Anki alternative, spaced repetition medical, Oncourse flashcards

