Options Strategies CFA Flashcards - Medical Study Cards
Master Options Strategies with Oncourse flashcards. These spaced repetition flashcards are designed for medical students preparing for NEET PG, USMLE Step 1, USMLE Step 2, MBBS exams, and other medical licensing examinations.
Options Strategies Flashcard Deck - 10 Cards
Flashcard 31: Put-call parity
Answer: synthetic long forward is equal to long the underlying.\
c0 – p0 = S0 – PV(X)
Put-call forward parity\
c0 - p0 = PV(F0(T)) - PV(X)\
F0(T) = forward price for a contract that matures at the same time as the options expire
Flashcard 32: Delta\
Gamma\
Theta\
Vega
Answer: Delta (Δ) = change in option price per +1 change in stock price.\
Delta is positive for (long) calls and negative for (long) puts.\
Gamma (Γ) = change in option delta per +1 change in stock price.\
Gamma is positive\
Theta (θ) = daily change in option price (effect of time passing).\
Theta is negative\
Vega (ν) = change in option price per +1% change in volatility.\
Vega is positive
Flashcard 33: The expected volatility of the percentage change in the market value of equity capital for a bank or insurer
Answer: 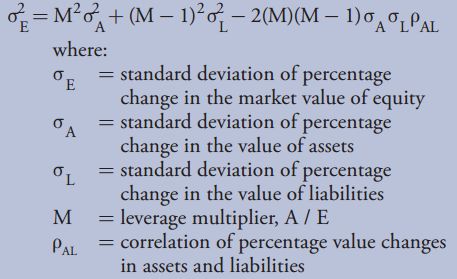
Flashcard 34: Straddle
Answer: A long straddle involves the purchase of an equal number of calls and puts on a given underlying. The options all have the same expiry date and strike.\
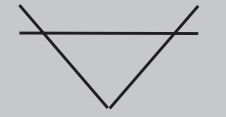\
A short straddle involves selling, instead of buying
Flashcard 35: Volatility skew
Answer: Implied volatility increases for more OTM puts, and decreases for more OTM calls. Explained by OTM puts being desirable as insurance against market declines while the demand for OTM calls is low.
Flashcard 36: Hedge Funds - Convertible bond\
type?
Answer: Relative value
the manager purchases the convertible bond which is often underpriced and short sells the underlying equity.
convertible bonds = regular bond + long call option on the corresponding stock
Flashcard 37: VIX Options\
• Call options gain in value if?\
• Put options gain in value if?
Answer: VIX Options\
• Call options gain in value if expectations of volatility at maturity of the option increase.\
• Put options gain in value if expectations of\
volatility fall.
Flashcard 38: Bull Spread
Answer: one long call with a lower strike price and one short call with a higher strike price\
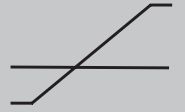
Flashcard 39: Variance notional in terms of Vega notional
Answer: 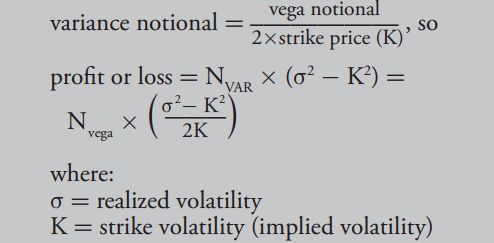
Flashcard 40: Callable bond\
Putable bond
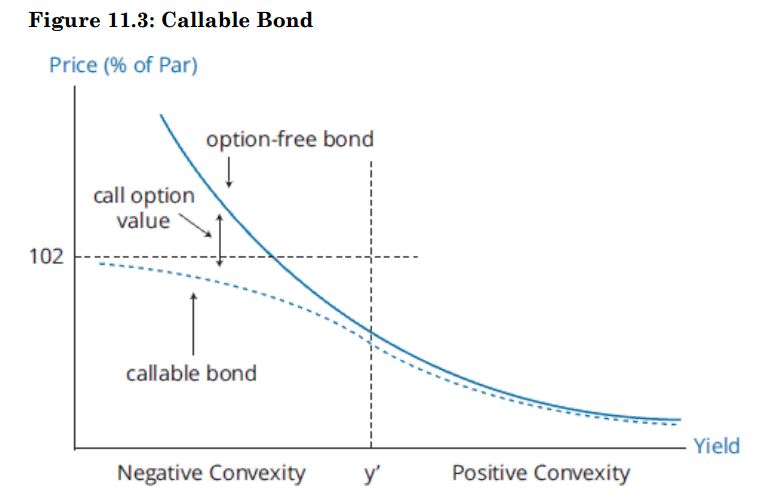
Answer: - A callable bond gives the issuer the right to buy the bond back from the investor before maturity.
- It can be viewed as a combination of an option-free bond and a short call option because this call has been granted to the issuer.
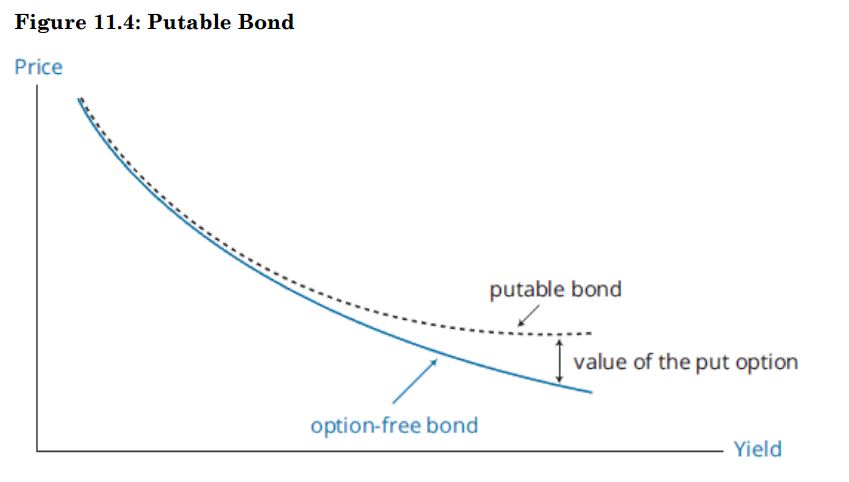
- A putable bond gives the investor the right to sell the bond back to the issuer before maturity.
- It can be viewed as a combination of an option-free bond and a long put option because this put is owned by the investor.
Keywords: Options Strategies flashcards, medical flashcards, NEET PG preparation, USMLE Step 1 flashcards, Anki alternative, spaced repetition medical, Oncourse flashcards

