Recommending changes in global portfolio weights on macro trends CFA Flashcards - Medical Study Cards
Master Recommending changes in global portfolio weights on macro trends with Oncourse flashcards. These spaced repetition flashcards are designed for medical students preparing for NEET PG, USMLE Step 1, USMLE Step 2, MBBS exams, and other medical licensing examinations.
Recommending changes in global portfolio weights on macro trends Flashcard Deck - 10 Cards
Flashcard 1: Black-Litterman
Answer: implied excess returns from a reverse optimization are adjusted to reflect the investor’s unique views, and then resolves for an EF.
Flashcard 2: **Risk premium approach to expected bond return**
Answer: 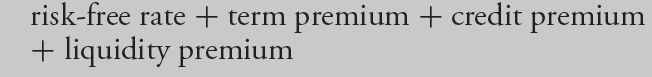
Flashcard 3: Black-Litterman Model (BL)\
*Asset Allocation*
Answer: The BL model requires several steps:
- Select a relevant, global index. Input market weights and covariance matrix.
- Use reverse optimization to solve for implied expected returns.
- Express an opinion regarding the returns.
- Adjust implied returns up or down based on opinion.
- A new MVO is run using the adjusted weights.
Flashcard 4: Covariance (Long)
Answer: Cov(i,j)=Beta(i,1)\*Beta(j,1)\*Var(F1) + Beta(i,2)\*Beta(j,2)\*Var(F2) + (Beta(i,1)\*Beta(j,2)+(Beta(i,2)\*Beta(j,1))\*Cov(F1,F2)
Flashcard 5: Approaches to Economic Forecasting
Answer: 1. Econometric Models
2. Economic Indicators
3. Checklist Approach
Flashcard 6: Z-Scores
Answer: 5% = 1.65\
1% = 2.33
Flashcard 7: Covariance
Answer: 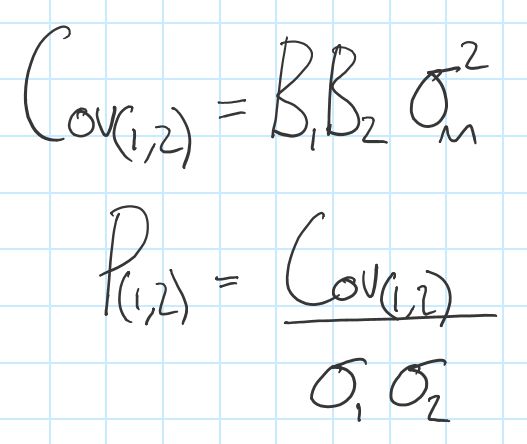
Flashcard 8: Financial Equilibrium Approach
Answer: The Financial Equilibrium Approach assumes that supply and demand in global asset markets are in balance. One such model is ICAPM:
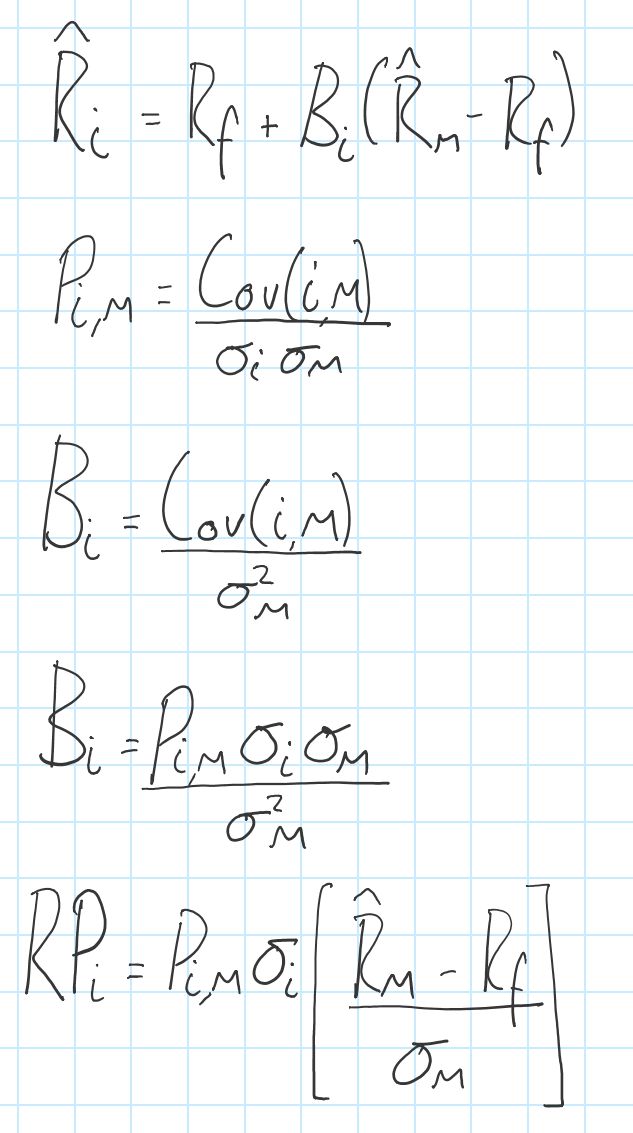
Flashcard 9: Commodities as an Inflation Hedge
Answer: Two factors affect whether a commodity is a good hedge against unexpected inflation: storability and demand relative to economic activity.
- Storable commodities have superior inflation hedging properties.
- Commodities that are most affected by the level of economic activity (energy, precious metals) tend to be better inflation hedges.
Flashcard 10: Singer and Terhaar
Answer: The Singer and Terhaar model adjusts the ICAPM for market imperfections, such as illiquidity and segmentation.
For illiquidity compare the expected return from ICAPM and the return necessary to equate its Sharpe ratio to that of the market to derive the illiquidity premium.
For segmentation take the weighted average of the equity risk premium at full integration and full segmentation.
Keywords: Recommending changes in global portfolio weights on macro trends flashcards, medical flashcards, NEET PG preparation, USMLE Step 1 flashcards, Anki alternative, spaced repetition medical, Oncourse flashcards

